Research
- Vice funds performance
- Measure contribution: largest datapoint(s) in a set that influence mean
- Maximum Likelihood Estimation
Fat Tails investing through machine learning
If betting on the fat tails through out-of-the-money options is a good strategy—meaning a strategy marketable to rational people and institutions—then it seems natural to ask, can an algorithm do it? Is it valuable to filter out human judgment at the trading level here? As it happens, Taleb has a paper that addresses this issue, forthcoming in the International Journal of Forecasting. It has some good news for ambitious coders. Taleb writes that his key function, g(x) [where g is a non-linear payoff function that “resembles financial derivatives term sheets] maps to various machine learning functions that produce exhaustive non-linearities.” His contention, specifically, is that many (human) misjudgments take place because humans focus on a variable (x) when they ought to be focused instead on the function of that variable, g(x). More intriguing, yet oddly confined to a footnote, is Taleb’s point in this connection that “machine learning of cross-entropy to gauge the difference between the distribution of a variable and the forecast” would be an effective way of capturing the nonlinearities of g(). Cross-entropy involves the calculation of the difference between two probability distributions, calculating the total entropy between them. It is used in machine learning as a loss function. The gist of this is that machines can learn over time to engage in information-theory judo, to make use of the loss of information to organize information and to capture those alpha promising nonlinearities.
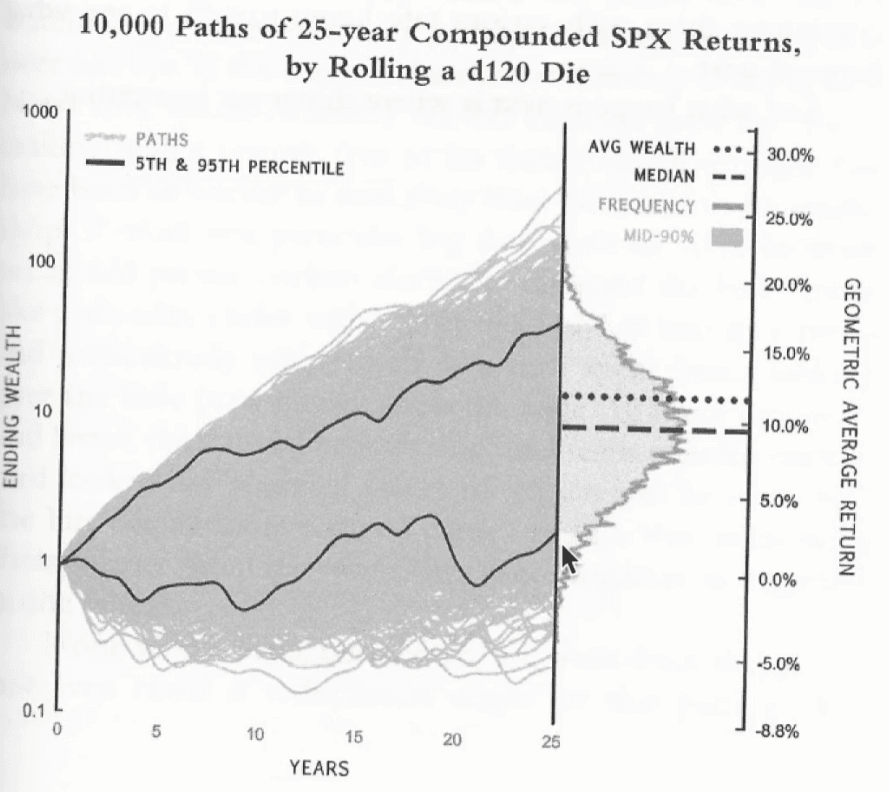 10.000 Paths of 25-year Compounded SPX Returns, by Rolling a d120 Die
5TH & 95TH PERCENTILE
AVG WEALTH
MEDIAN
FREQUENCY
MID-90%
X axis: years
Y axis: GEOMETRIC AVERAGE RETURN
Missed opportunities Date - TobinQ eq Q Apr 82 - .28 Jan 2003 - 0.85 Jan 2009 = 0.66
Early 2016 downturn Aug 2015 flash crash June 2016 UK something Nov 2016 - VIX spike Feb 2018 - xmas crash 2020 - stock market crash
Tobin's equity Q ratio
Upper 3rd / 4th quartiles
0.5% per month
2 month puts that are 30% out of the money
